How to Value Patents, Trademarks and Other Intellectual Property in Singapore
While patents, trademarks, software, and other intellectual property (IP*) can actively generate revenue, protect market share, and secure a distinct competitive advantage, an intangible asset’s (IA*) value depends on far more than its initial registration or development costs. Instead, its overall value is driven by a complex combination of factors including, commercial demand, future income potential, remaining useful life and legal enforceability.
To accurately measure these factors, Intellectual Property Valuation Services help businesses estimate market or fair value for critical use cases like transactions, licensing, financial reporting, corporate tax strategies, and dispute resolution. In Singapore, determining this value requires a specialised approach tailored strictly to the specific intangible asset being assessed, the purpose of the assignment, and the depth of verifiable market evidence available.
*IP is a specific subset of the broader category of intangible assets. IP stems from human intellect and grants exclusive statutory rights to the owner based on legal enforceability by way of a copyright or a trademark or a patent or a trade secret.
What Determines the Value of Intellectual Property?
Before selecting a valuation method, the valuer needs to understand the IA in some detail including, the underlying technology, if any, its uniqueness, its commercial role, its useful life and the legal rights attaching to it. Key factors include:
- Revenue and market demand: Licensing income, product sales, customer demand and the IA’s contribution to profitability help establish its value.
- Remaining useful life: A patent nearing expiry or software approaching obsolescence may have a shorter period in which to generate economic benefits.
- Competitive position: Alternative technologies, competing brands and changes incustomer preferences can reduce future earnings.
- Commercial risks: Development costs, regulatory constraints, infringement disputes and uncertainty around future adoption can affect projected returns.
- Legal protection: Ownership, registration status, geographical coverage, enforceability and remaining protection period can affect an asset’s commercial potential.
A registered patent or trademark is not automatically valuable simply because it is legally protected. Its value depends on the economic benefits it can reasonably deliver.
What Are the Main Intellectual Property Valuation Methods?
Three recognised approaches are commonly used to value intellectual property. The choice depends on the IA’s maturity, income-generating potential and the availability of reliable market or cost data.
1. Income Approach
The income approach estimates the future economic benefits or cashflows attributable to an IP asset and discounts those to present value, accounting for risk and the time value of money. It is often useful for commercialised patents, software and established brands.
Two techniques are particularly relevant:
- Relief-from-royalty method: Estimates the royalties a business would hypothetically pay to license the trademark or copyright from another owner. The projected royalty savings are discounted to present value.
- Multi-period excess earnings method (MEEM): Estimates the cash flows attributable to a particular intangible asset after deducting appropriate returns for other tangible or intangible assets that contribute to those earnings.
For example, a trademark used by an established business may be valued using projected sales, an appropriate royalty rate and the remaining economic life of the brand.
2. Market Approach
The market approach uses prices or licensing rates from comparable IP transactions. It can provide useful evidence when similar IPs have been licensed under sufficiently comparable conditions.
However, patents and proprietary technologies are often unique. Differences in exclusivity, market potential, contractual terms and legal protection can make direct comparisons difficult. The valuer must assess whether the available evidence is genuinely comparable.
3. Cost Approach
The cost approach estimates the cost of recreating or replacing an IP with one offering equivalent utility. Depending on the IP, this may include relevant development, technical and testing costs, adjusted inflation (if historical costs are used) and for economic and technology obsolescence.
It can be useful for certain early-stage technologies or assets without reliable income forecast. However, the cost of developing intellectual property does not necessarily equate to its value. Expensive research may produce little commercial benefit, while a relatively inexpensive innovation can generate substantial financial returns.
For complex technology IPs, comparing income-based estimates with cost-based evidence can help test whether the valuation assumptions are reasonable.
When Should a Business Obtain an IP Valuation?
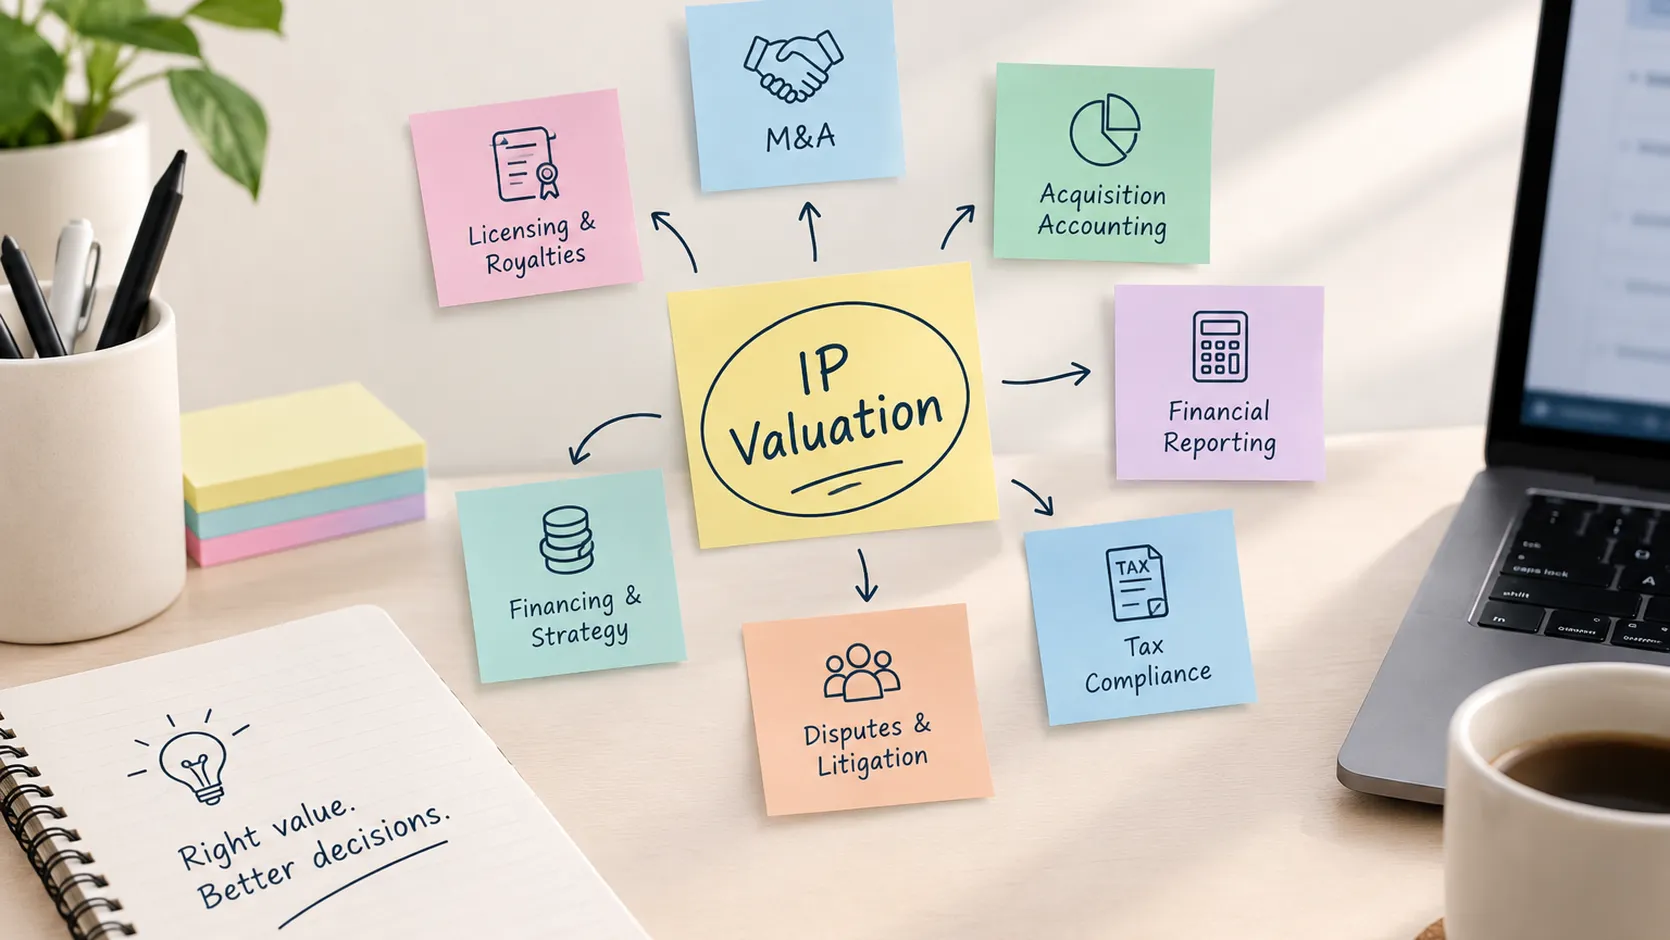
Businesses may need an independent valuation when they are:
- Buying or selling a company, patent, trademark or software asset.
- Negotiating a licence or royalty arrangement.
- Allocating acquisition consideration to identifiable intangible assets.
- Assessing impairment for financial reporting.
- Supporting qualifying tax requirements.
- Resolving disputes involving ownership, licensing or economic loss.
- Evaluating IP portfolios for financing or strategic decisions.
The valuation should be scoped around the intended use. A report prepared for a transaction may require different assumptions and disclosures from one prepared for financial reporting or tax compliance.
Intellectual Property Valuation by Spring Galaxy
Spring Galaxy delivers expert intellectual property valuation services in Singapore, providing commercially relevant and defensible reports that help clients make strategic decisions with confidence. Drawing on tested methodologies and sector-specific insights, our team determines the fair value or market value of patents, trademarks, copyrights, software, brand names, and trade secrets.
Headquartered in Singapore with offices in Malaysia, Indonesia, Thailand and Laos, Spring Galaxy provides robust, insight-driven valuation solutions tailored across the Asia Pacific region. Our valuations ensure transparent financial reporting, align with local regulatory frameworks, and effectively support clients through fundraising, legal disputes, M&A transactions, and tax compliance.
To conclude
The market value of an intellectual property asset depends entirely on the future commercial benefits it delivers, its inherent risks, and the evidence backing the assessment. Because every IP is unique, choosing the right valuation methodology and defining the assignment’s purpose clearly is essential to producing a robust, defensible report.
Securing an independent, expert valuation ensures complete alignment with regional regulatory frameworks, giving businesses the precise data needed to navigate cross-border transactions, tax guidelines, and financial reporting with confidence.
Business valuation is the process of determining the economic worth of a company through financial analysis, market comparisons and asset assessments. It is essential for M&A transactions, fundraising, legal disputes, succession planning, financial reporting and strategic decision-making.
Key triggers include selling or acquiring a business, raising capital from investors, settling shareholder disputes, complying with regulatory requirements, planning an IPO, restructuring debt, or conducting annual financial reviews.
The three primary approaches are: the Income Approach (Discounted Cash Flow), the Market Approach (comparable company analysis and precedent transactions), and the Asset-Based Approach (net asset value). The most appropriate method depends on the nature and stage of the business.
A standard valuation engagement takes between 2 to 6 weeks, depending on the complexity of the business, the availability of financial data and the purpose. Complex or contested valuations may take longer.
Valuers typically require audited financial statements (3–5 years), management accounts, business plans, a list of assets and liabilities, shareholder agreements, key contracts and relevant industry or market data. Exact requirements vary by engagement.
Book value is the net asset value recorded on a company's balance sheet. Market value reflects what a willing buyer would pay a willing seller in an arm's-length transaction — often significantly different due to goodwill, intangibles and market sentiment.
IP valuation employs cost-based, market-based and income-based approaches. The Relief-from-Royalty Method is widely used for patents and trademarks, while the Multi-Period Excess Earnings Method is common for customer relationships and proprietary technologies.
Certified valuers adhere to international valuation standards (IVS, RICS, NACVA), produce defensible reports accepted by courts, regulators and investors, and provide objective, independent analysis free from conflicts of interest.
